Compare employers' liability insurance
Safeguard your business with employers' liability insurance
Find the right business insurance for you
Answer some simple questions about your business.
Pick the covers you need, leave the ones you don’t.
Get insured within minutes.
1,000+ Business types covered by Superscript’s business insurance.
Why Superscript?
Pick the covers you need, leave the ones you don’t.
Get instant proof of cover.
Hassle-free claims and UK-based customer support.
Rated 'excellent' on Trustpilot.
Business insurance, sorted in minutes
Share some business details and unlock tailored insurance choices in just a couple of minutes.
What is employers' liability insurance?
Employers' liability insurance is a form of business insurance that protects employers if their employees become ill or injured while carrying out their work. It covers the costs of legal expenses, compensation payments, and other associated costs resulting from claims made by employees. This not only safeguards your business from potentially significant financial losses, but also provides peace of mind.
In the UK, businesses usually have a legal requirement to hold employers’ liability Insurance if they have one or more employees. Despite this, Association of British Insurers research found that, as of January 2026, some 39% of SMEs with 1 to 9 employees didn’t have compulsory employers’ liability insurance, putting them at financial and legal risk.
Business liability claims are costly. Without adequate cover, a single claim could have a devastating impact on a business’s finances.
Who needs employers' liability insurance?
Employers’ liability insurance is a legal requirement for most businesses in the UK, ensuring protection for anyone working for you. It safeguards your business from claims if an employee is injured or falls ill due to their work.
It's usually needed if you employ:
Full-time and part-time employees
Self-employed contractors (unless they provide their own tools and work entirely independently)
Temporary staff, apprentices, volunteers (working under contract)
Anyone on work experience
Some people on training schemes
If you’re required to have a policy, it must cover at least £5 million and be provided by an authorised insurer. Not having adequate cover can lead to significant penalties:
£2,500 per day for not having the required insurance
£1,000 if you fail to display your Employers’ Liability Certificate where staff can see it, or if you refuse to show your insurance certificate to an inspector when asked
Business success stories
Case study
“Test as you go. Don’t just fall in love with an idea and rush into production.”
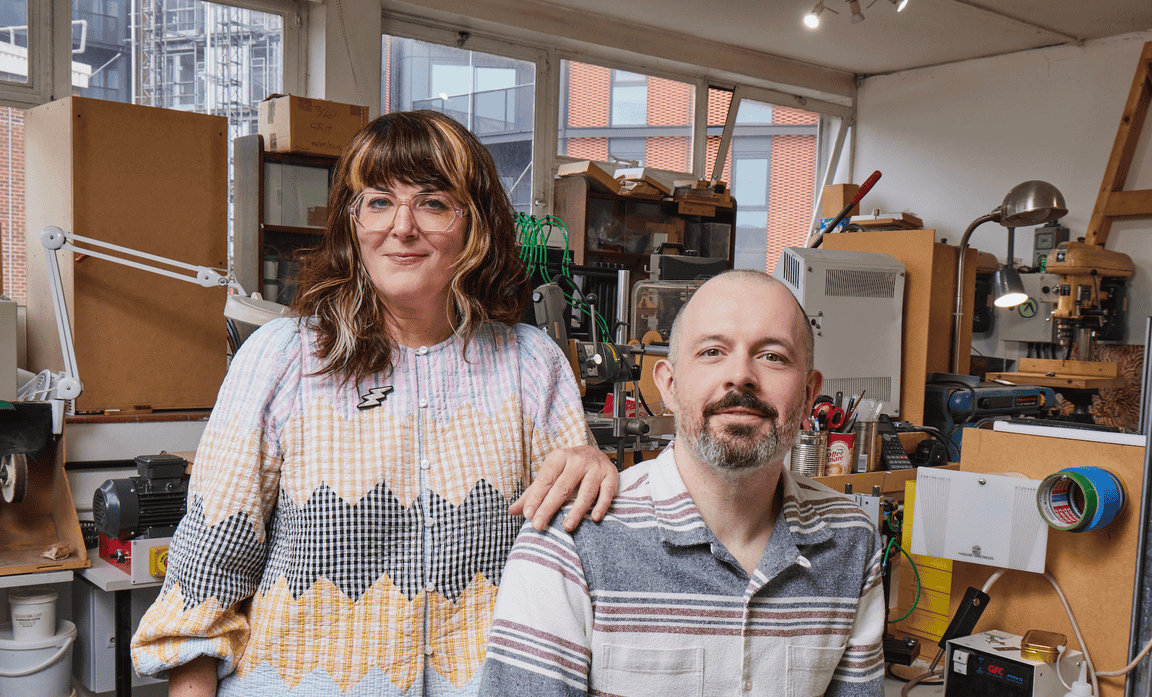
Natalie Edwards and Matthew Lambert founded The House of Spectacles to address a widespread eyewear issue – most glasses simply don’t fit properly.
Years of refining the craft, testing designs, and learning from customers have allowed them to create eyewear that truly empowers people to feel confident and comfortable.
When you might not need employers' liability insurance
While employers’ liability insurance is a legal requirement for many businesses, there are specific situations where it may not be necessary.
For example, you may not need to purchase it if:
You run a family business and only employ close family members (unless your business is a limited company)
You run a company in England, Scotland or Wales and employ someone who is based outside Great Britain, or you run a company in Northern Ireland and employ staff based outside the UK
Your business is a public organisation, health service body, or another exempt publicly funded organisation
Your business is a limited company with no employees other than yourself, and you also own 50% or more of the share capital
Self-employed people who don’t employ anyone
If you’re unsure about your legal obligations, it’s always worth seeking advice before making any decisions and consider the differences between different types of cover like public liability.
What does employers’ liability insurance cover?
Covered
Not covered
Employers' liability insurance: example claim scenarios
A worker at your construction site falls from some scaffolding, breaking their left leg. They file a claim for medical expenses and lost wages. Employers' liability insurance can help you to cover the compensation costs, including any legal fees.
One of your employees trips over a loose cable in the office and badly injures their right ankle. They end up needing treatment and time off work. The insurance can cover medical bills and any compensation for lost earnings.
An employee who works in your toy shop starts to suffer from repetitive strain injury due to poor ergonomics while working at the checkout. Employers' liability insurance can cover the costs of treatment and compensation for their time off.
A waiter working at your hotel inadvertently serves a dish with an allergen to a customer who suffers a severe allergic reaction. While public liability insurance would cover customer claims, employers' liability insurance could come into play if the employee’s actions were the result of inadequate or inaccurate training.
A delivery driver employed by your logistics company suffers a lower back injury while lifting heavy packages. Employers' liability insurance could help cover medical expenses, rehabilitation costs, and compensation for the employee’s recovery time.
Employers' liability insurance: example claim scenarios
Construction site accident
Office injury
Retail employee illness
Food allergy
Warehouse incident
What determines the cost of employers' liability insurance?
The cost of employers’ liability insurance depends on several factors, including the nature of your business, the size of your workforce, and the level of risk involved in your operations.
The main things that will be taken into account are:
Industry: The level of risk associated with your business operations will influence the cost. High-risk industries — construction and manufacturing, for example — will generally face higher premiums owing to the greater likelihood of workplace accidents.
Business size: Larger businesses with more employees will typically pay higher premiums. The more individuals, the higher the potential cost of claims.
Coverage level: The amount of coverage you need will also affect your premium. The legal minimum cover is £5 million, but you might decide to choose higher limits depending on the nature/size of your business.
Claims history: If your business has a history of making claims then insurers could regard your business as riskier than another similar operation. This could lead to higher premiums.
Health and safety record: A strong health and safety record can help lower premiums, as insurers are likely to view your business as having a lower risk of workplace accidents.
Be mindful of the fact that insurers will assess risk factors slightly differently. Comparing quotes from different providers can ensure you’re best placed to find the coverage that works for your business.
How to choose an employers' liability insurance policy
Choosing the right employers’ liability insurance policy is an important business decision. Here’s a step-by-step guide to help you make the right choice.
Determine if you need it
Identify the cover you need
Compare quotes
Review the policy documents
Purchase the policy
How much does employers’ liability insurance cost?
Employers' liability insurance costs vary based on factors like business size, industry risks, and claims history, with larger businesses typically paying more.
Comparing quotes can help you find the right coverage at the best price.
| Business Activities | Monthly premiums from* | Monthly premiums to** |
|---|---|---|
| Professional services | £0.78 | £12.32 |
| Technology | £0.81 | £14.93 |
| Marketing | £0.86 | £13.93 |
| Hair and beauty | £0.76 | £13.20 |
| Tradespeople | £3.25 | £64.00 |
| Food and drink | £0.76 | £8.81 |
*Superscript: Superscript: 10% of customers paid this much, or less, between July and September 2024 when bought with public liability insurance.
**Superscript: Superscript: 90% of customers paid up to this much between July and September 2024 when bought with public liability insurance.
These prices should only be used as a guide. When you get a quote, it will be tailored to your unique circumstances and risk profile – so you may be quoted a price that’s a bit higher or lower.
And as with most covers, price shouldn’t be your only priority. Cheaper insurance could end up costing you more if it doesn’t provide the cover you need. To get the best deal, look for insurers that allow you to tailor your policy to your needs so you're not left over- or under-insured.
“Employers' liability insurance protects businesses from the financial impact of workplace accidents or claims, offering peace of mind and ensuring your employees are safeguarded.”
How to make a claim on your policy
If an employee suffers an injury or bout of illness at work and you need to make a claim on your employers’ liability insurance, these are the steps that you will likely need to take.
Report the incident
Provide supporting evidence
Cooperate with any investigation
Other types of insurance to consider: bundle for comprehensive coverage
When it comes to protecting your business, it’s important to consider more than just employers’ liability insurance.
Public liability insurance: This covers damage caused by your business to a third party or their property. A third party is usually anyone who isn’t employed by your business.
Professional indemnity insurance: This covers claims arising from mistakes, errors, or omissions in the advice or services provided by you or your company. It protects against legal costs and compensation making it suitable for startups.
Goods in transit insurance: This covers loss, damage, or theft of goods belonging to clients or customers while they’re being transported. It provides protection during the journey, whether shipping products or delivering services.
Tool insurance: If your business relies on tools — whether small items like hammers and saws, or larger equipment like diggers — tool insurance can be invaluable. It covers the cost of replacing essential tools and equipment if they’re lost, stolen, or damaged.
Shop insurance: Shop insurance protects your business from risks like damage to property, theft of stock, or customer claims related to items sold. It also covers situations such as shop closure due to flooding.
FAQs
Employers' liability insurance is not always required in certain situations. For example, you may be exempt if you only employ close family members (such as a spouse, parent, or child). Sole traders without employees, partnerships with equal partners and no employees, or employees working abroad under non-UK contracts are among the other categories that may also be exempt.
Whether you need this cover for contractors and sub-contractors depends on their contract. It may not be needed where you employ independent contractors or bona fide sub-contractors, as they supply their own tools and equipment, and don’t work under your direction.
The amount of employers' liability insurance you’ll need depends on several factors, including the size of your business, the industry you operate in, and the level of risk associated with your employees’ roles.
Here’s how to determine the right level for your business:
Legal requirement: By law, you must have a minimum of £5 million in coverage if you employ anyone (other than immediate family or other specific exempted parties). If your business is likely to encounter risky situations — as can happen in sectors like construction or manufacturing — you may need more coverage.
Number of employees: Larger businesses with more employees may need higher coverage to ensure all members of staff are protected.
Potential claims size: If your business deals with high-value claims, or operates in an industry that is prone to expensive lawsuits, it’s probably worth considering a higher coverage level.
Additional coverage: You might also want to consider adding extra coverage, such as public liability, for even more comprehensive protection and extra peace of mind. It’s important to carefully assess the unique risks associated with your business before choosing a policy.
A policy typically lasts for 12 months, and will nearly always come with the option to renew at the end of the term. Your insurer will usually contact you around 30 days prior to the policy expiring to remind you and offer renewal options. This is a good opportunity to review the policy to ensure it’s still fit for purpose; if you’ve hired more staff, or the business has taken on new responsibilities, you may need to update or adjust your coverage.
If you’re legally required to have employers’ liability insurance but don't secure adequate cover, you could be fined up to £2,500 for each day you operate without it. This applies even if your employees are temporary, part-time, or casual workers. You can also be fined £1,000 if you fail to display your employers’ liability certificate or refuse to make it available to inspectors upon request.
Public liability insurance covers claims made by third parties — generally customers or members of the public — for injuries or property damage caused by your business activities. Employers’ liability insurance, on the other hand, covers claims made by employees who are injured or become ill as a consequence of carrying out their work. This type of insurance is very often a legal requirement if you employ staff (though there are some exceptions), and ensures you’ll be protected if an employee files a claim for any workplace-related incident.
Yes – you need to display your employers' liability insurance certificate in a prominent place where it can be easily seen. This can be a physical copy displayed at your workplace — staff room, kitchen, reception area — or can be digital, as long as it is readily accessible to employees. A failure to display the certificate or make it available to inspectors upon request could result in a fine of up to £1,000.
No, you don’t have to pay an excess to claim on your employers' liability insurance. The policy is designed to cover the cost of compensation and legal fees if an employee makes a claim against you, ensuring your business is protected without any additional expenses.
You need employers’ liability insurance as soon as you hire employees, even if they’re temporary, part-time, or contractors and subcontractors you manage. The policy must be provided by an authorised insurer. This insurance protects your business by helping to cover compensation costs if an employee is injured or becomes ill as a result of their work.
Employers' liability insurance is mandatory if you have volunteers who are under contract or instructed on their duties. It is recommended for those who work on an ad hoc basis . You and the business have a duty of care to provide a safe working environment for anyone working as a member of your team.
Yes, employers' liability insurance will typically cover a claim made by a former employees, provided the incident in question occurred while they were employed by your business. For example, if a former employee develops a workplace-related illness or injury after leaving your company, they may still be in a position to file a claim.
It's important to note that coverage will apply to incidents that occurred during the active policy period, so maintaining continuous coverage is crucial. Additionally, some policies may include specific conditions or timeframes for reporting incidents, so always check your policy details to ensure you're protected over the long term.
Yes, employers' liability insurance is typically required for remote workers if they are considered employees of your business and are based in the UK. It covers work-related injuries or illnesses, even if the work is done remotely. The requirement remains the same regardless of whether employees work in-office or from home, so long as they are on your payroll.
Be sure to check specific local regulations to ensure full compliance.
Discover our business insurance guides
About the author
Didn't find what you're looking for?
See what other sorts of insurance could be right for your business
Other business products you might need
Customer Reviews
Everything you need to gain credit for…
Very fast and efficient. From start to finish it was easy to follow the application.
Great website
We’ve been featured in